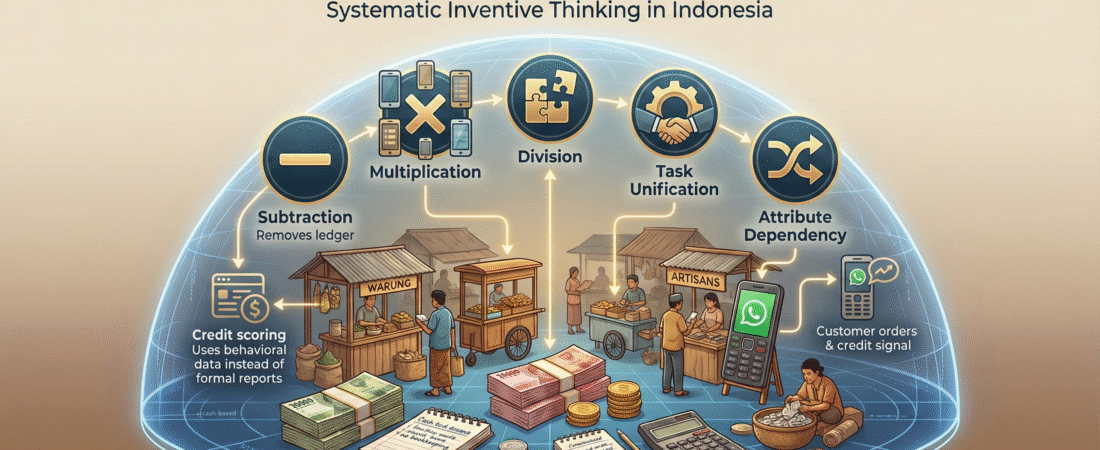
Innovating is hard. We need to come up with a new method, new idea, new product. We need to dig deep and think about the non-obvious yet powerful solution. There are many tools that can help us innovate like Design Thinking, Lean Startup, etc. In this particular post, we are going to discuss one particular thinking tool. It is Systematic Inventive Thinking (SIT). We will explore how it can be used to help us rethink MSME Credit in Indonesia.
Systematic Inventive Thinking (SIT) and It’s Core Philosophy
I first encountered Systematic Inventive Thinking (SIT) during my MBA. What struck me instantly was its core philosophy: the world is closed.
No new resources. No new processes. You innovate strictly within what already exists.
SIT forces you to treat the current constraints as non-negotiable design rules. You don’t solve problems by adding more, you solve them by reconfiguring what you already have. A breakthrough happens when you change how you use existing resources. It also occurs by altering how you process the situation, not by expanding your toolkit.
This runs against our natural instinct. When we face a problem, our default response is to look for more. We seek more money, or more time, or more people, or more tools.
Take a common example: “I want to start a business but I have no money.” The typical question becomes: “How can I raise money so I can start my business?” That question already assumes the missing resource must be acquired.
SIT flips that completely. It asks you to accept the constraint and innovate within it. So the question becomes: “How can I start my business given that I have no money?”
This is the essence of SIT: creativity not by addition, but by transformation under constraint. We face constraint in every aspect of our life. That’s why SIT can be a very powerful tool.
SIT Toolkit
There are 5 different tool within SIT method. Here is a simple explanation of each tool.
| SIT Tool | Simple Meaning | Everyday Example |
| Subtraction | Remove something essential | Mobile-only bank, no branch |
| Multiplication | Copy something with a twist | Multiple phone lenses that function differently (tele, macro, wide, etc.) |
| Division | Break and rearrange | Pay-per-class gym |
| Task Unification | One thing does two jobs | Car mirror that also act as a turn signal |
| Attribute Dependency | One change triggers another change | Prices rise during rain |
Implementing SIT on MSME Credit in Indonesia
Now, on our last post, we discussed about how How to Lend to MSMEs in Indonesia When Bookkeeping Doesn’t Exist. We also discussed about the four major constraints of MSME lending in Indonesia.
- Most of the transactions are still cash-based.
- Non existent book keeping means loss of data. Information about cash flow, revenue, cost, profit, and margins is missing. Details on working capital needs and payment schedule are also gone.
- Most of them mix personal and business money.
- Loans are obtained through informal channels. They can’t be traced reliably. Thus, we can’t fully understand how much total debt the business has.
We also discussed that transaction digitalization will eventually came but it will take many years. The only way to move ahead with the challenges surrounding the MSME credit in Indonesia is to accept the constraint. We must innovate within it. That’s why SIT become the right thinking tool for this particular problem.
Let’s run a high-level innovation thinking using the five thinking tool of SIT. I won’t go into too much details. This exercise is just to show the general process of innovation using SIT.
1. SUBTRACTION
Remove the dependence on “perfect financial data.”
Instead of requiring formal reports, identify which signals still exist even when data is missing.
Examples of removed dependencies:
- Remove need for sales reports → use visible business activity
- Remove need for formal debt numbers → use behavioral stability
- Remove need for detailed cost breakdown → use restocking patterns
Outcome:
A credit model that works even when financial records are absent.
2. MULTIPLICATION
Take an existing MSME behavior and create multiple useful signals from it.
MSME owners already:
- Buy supplies
- Serve customers
- Pay bills
- Chat on WhatsApp
Each behavior can be “duplicated” into several credit indicators with minimal effort.
Outcome:
One action produces multiple insights.
3. DIVISION
Break creditworthiness into smaller pieces so each part can be assessed using simple observations.
Instead of asking:
“Is this business financially healthy?”
Split it into components like:
- Is demand stable?
- Are suppliers being paid?
- Is inventory moving?
Each piece is simpler, observable, and doesn’t need formal data.
Outcome:
Complex assessment becomes manageable.
4. TASK UNIFICATION
Make one activity serve BOTH the business operation and credit assessment.
Examples (conceptually):
- Supplier invoices → inventory + credit signals
- Utility payments → household + discipline signal
- Customer orders on WhatsApp → sales + stability signal
Outcome:
No extra work for the MSME, yet valuable data emerges.
5. ATTRIBUTE DEPENDENCY
Link real-world patterns to credit scoring automatically.
For example:
- If inventory moves faster → inferred higher sales → score rises
- If supplier payments stretch longer → stress indicator → score drops
- If order frequency increases → dynamic limit increases
Outcome:
A living, adaptive scoring model built from ordinary business rhythms.
The high-level punchline:
SIT allows innovation in MSME credit assessment. It turns everyday behaviors into credit signals. This innovation does not require formal bookkeeping or digital literacy.
This is the conceptual foundation.
Anyone building a solution can now expand it into:
- scoring models
- product features
- data pipelines
- field operations
- lending strategies